At least it is in the insurance industry.
It’s tough enough that some insurers aren’t writing new property policies or are exiting the market completely, including cancelling and non-renewing existing policies. The ones that remain are being very picky about what they’ll write and one thing that will generate a non-renewal or cancellation notice: Your roof.
You think your roof has a 30-year life, right? The insurance industry doesn’t think so. Some insurers will not write a roof more than 15 years old. Moderate wear and tear? Cancellation may be pending.
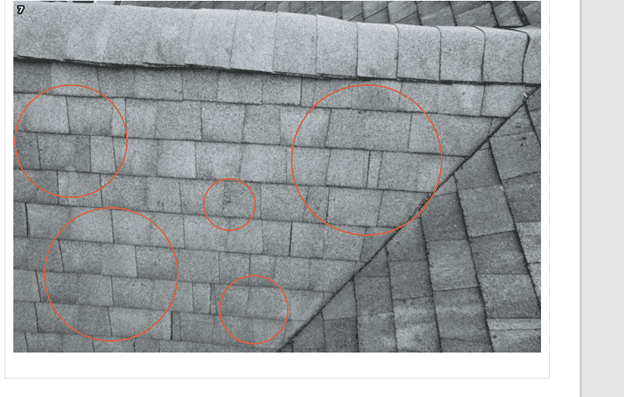
Seriously, look at this photo. There’s other issues, but do you see anything deserving of red circles indicating a problem? Utica First Insurance Company issued cancellation due to conditions.
Want more? One insurer has told us to limit the number of new business policies we send to them to a certain number of roofs per month. Not by policy count – send in all the renters and condo policies you want because they don’t have roofs that are covered by the occupants policy – but explicitly by number of roofs.
Part of it isn’t the insurers, it’s the rules imposed on them by the state. That’s a different post.
Higher deductibles are also trending. Minimum $1000 homeowners deductible? Yes, we’re seeing that with at least 1 company. Probably more to come. And look out for that ‘percentage’ deductible, especially if you’re anywhere near the coast.
We’ve been anticipating that the market would ease up for nearly 2 years now. But now we’re starting to think that this is the new normal. You need an agent.
#Roof #HomeownersInsurance #PropertyInsurance #CTInsurance #InsuranceAgent